Subscriber Benefit
As a subscriber you can listen to articles at work, in the car, or while you work out. Subscribe Now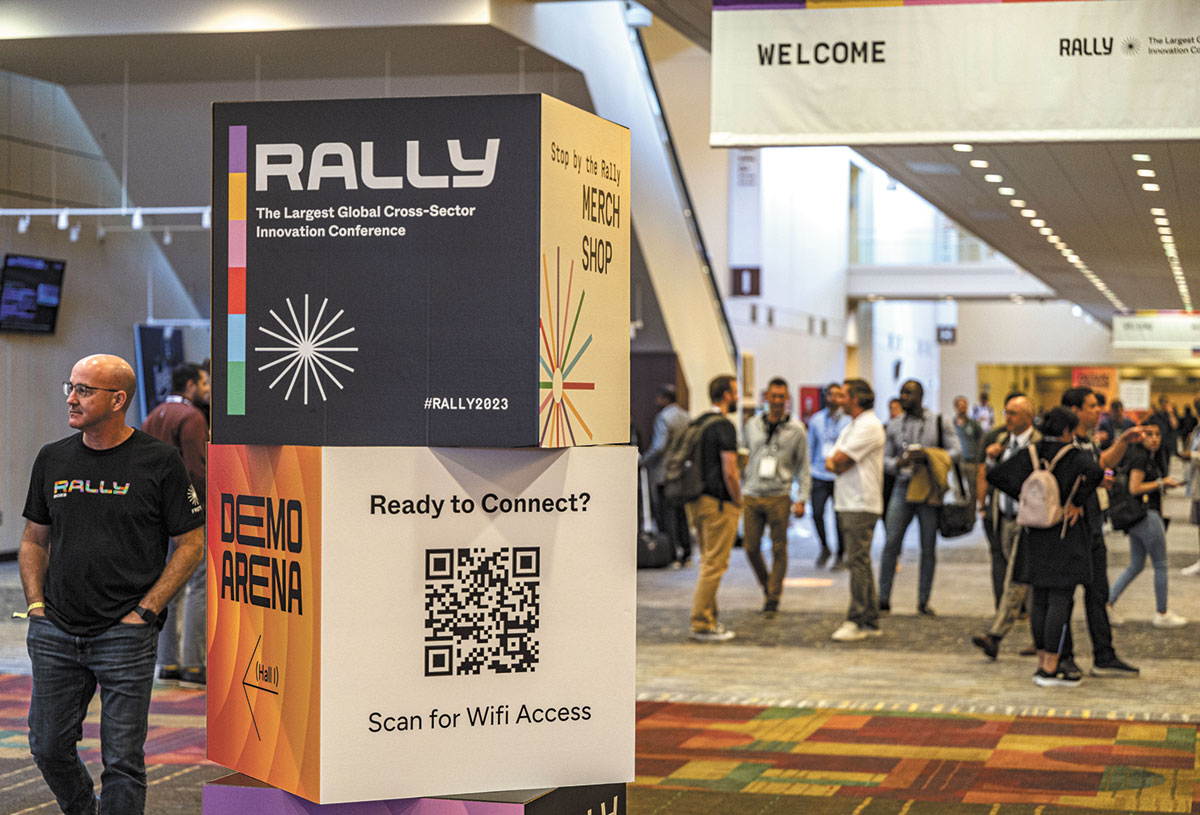
Over the past few months, Jeb Banner and fellow entrepreneurs have puzzled over this question: What the heck is happening with Elevate Ventures?

“This is something that’s being discussed across the community,” said Banner, former CEO of live music booking and marketing software company Opendate. Banner has also founded or co-founded numerous Indianapolis entities, including board-management software firm Boardable; and The Speakeasy, a nonprofit coworking and entrepreneurial support organization that ceased operations at the end of last year. “Nobody really knows what’s going on.”
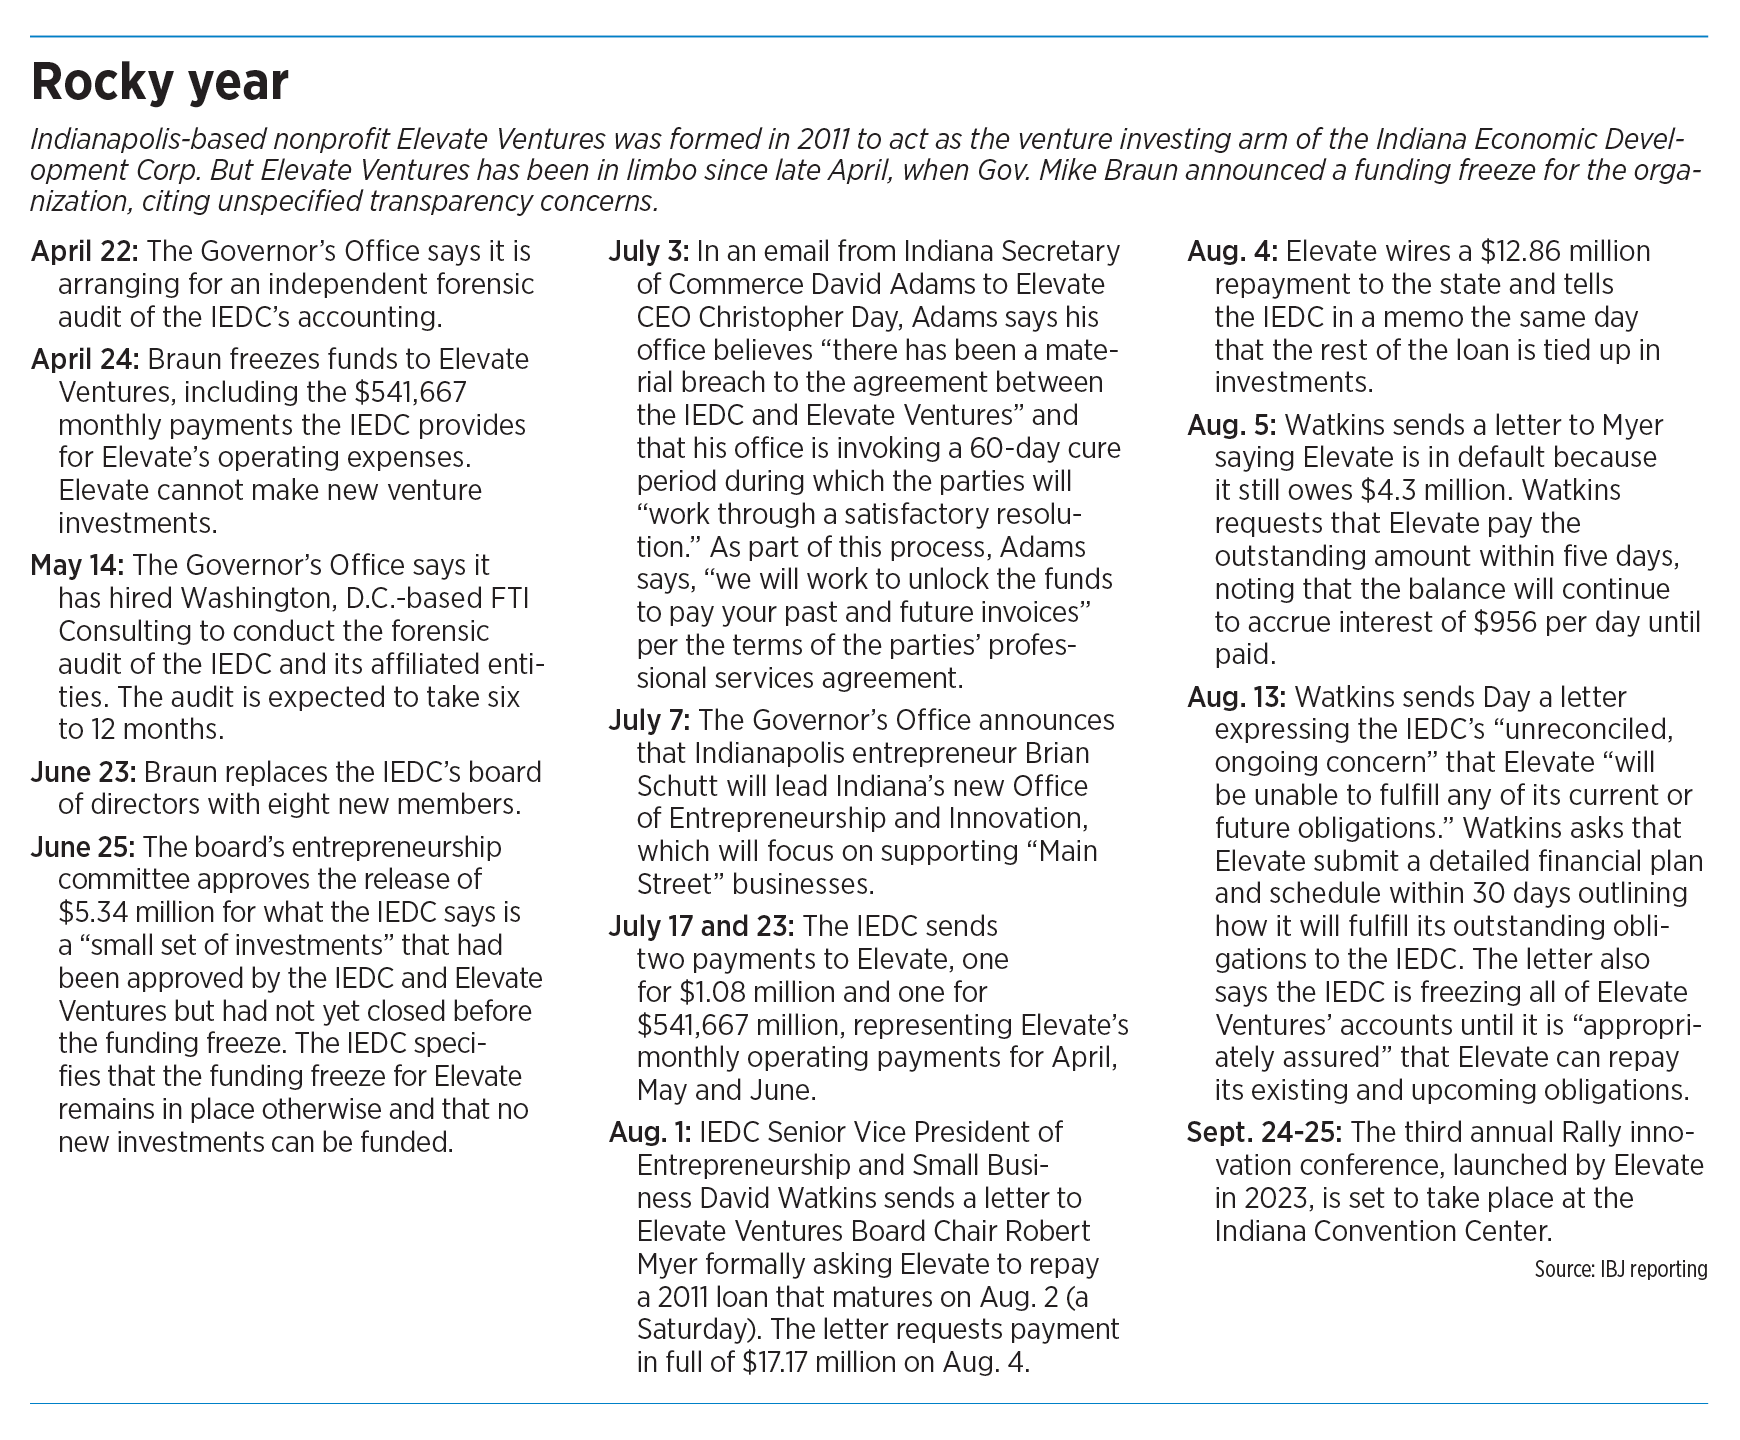
Indianapolis-based Elevate, a nonprofit that has managed venture investing and startup development on behalf of the Indiana Economic Development Corp. since 2011, has been operating under a cloud since late April. That’s when Gov. Mike Braun’s office called for an independent forensic audit of the IEDC, citing unspecified transparency concerns and potential wrongdoing with its partner organizations.

On April 24, Indiana Commerce Secretary David Adams said the state would freeze the transfer of funds to Elevate, preventing the organization from investing in Indiana startups—its core function. The freeze also applied to the $541,667 in monthly payments the IEDC provides to Elevate for operating expenses such as salaries and programming costs.
“We’re going to place those funds on hold until further evaluation,” Adams said in April.
Since then, the situation has escalated, with the state accusing Elevate of defaulting on a 14-year-old convertible note—a loan the state could have converted into an ownership stake— and threatening to freeze Elevate’s bank accounts, even though the organization is not under state control.
The conflict is a troubling situation for Indiana’s startup and entrepreneurship community, given Elevate’s role in supporting young companies around the state, observers told IBJ.
“Elevate has played a pretty important role … in catalyzing the formation of these companies and allowing them to have enough time to mature to the point where the later stage funds and out-of-state money can come in,” said Kristian Andersen, a co-founder and partner at Indianapolis-based venture studio High Alpha.
Traditional venture investment firms typically don’t make those types of very small investments in nascent companies—and Indiana has a dearth of investors focused on early-stage investments. So having an entity like Elevate is important, Andersen said.
As two examples, Andersen cited Indianapolis-based software companies Lessonly and Octiv Inc., both of which he co-founded with several other partners. “Both of those companies received funding from Elevate and went on to have spectacular exits,” Andersen said.
(Octiv, founded in 2010 and originally named TinderBox, was acquired by Broomfield, Colorado-based Conga in 2018. Lessonly, founded in 2012, was acquired by San Diego-based Seismic in 2021. Financial terms for those deals were not publicly disclosed.)
Andersen said Elevate and High Alpha, which launched in 2015, have also been co-investors in a handful of other deals over the years.
Filling ‘a big void’
Prior to the April funding freeze, Elevate was “helping an awful lot of companies,” said Nick Mathioudakis, an Indianapolis business attorney and a partner at Faegre Drinker Biddle & Reath LLP. “They really did fill a big void.”
Mathioudakis represents both tech companies seeking capital and investors who provide capital. Over the years, he has represented dozens of clients who have sought investment funding from Elevate.
According to Elevate’s 2024 annual report, the organization made 103 investment commitments totaling $18.9 million. Of those 103 commitments, 61 came from Elevate’s pre-seed fund. Elevate’s pre-seed investments are typically between $20,000 to $100,000 and made into Indiana-based companies at their earliest stages—startups that that might only have an idea or an undeveloped technology and are therefore unattractive to the typical venture investment firm.
The money that Elevate invests comes from a mix of state and federal funding, all funneled to it from the IEDC. In late April, Elevate officials told IBJ that about 80% of the money it has invested in early-stage startups over the past few years has come from the State Small Business Credit Initiative, a U.S. Treasury Department initiative to invest in small local businesses.
Since its establishment in 2011, Elevate has invested a total of $184 million in 602 startups across Indiana. The lion’s share of those investments—$125.4 million, or 68% of total investments to date—have gone to companies in four counties: Marion, Hamilton, Boone and Hendricks.
“To neuter Elevate, if that’s the goal here, would have a huge ripple effect on the early-stage businesses in this community,” Banner said.
So Banner, and others, have a lot of questions about how the ongoing conflict will be resolved.
“I’m glad you’re writing about it—and maybe [state officials] can provide more insights about where things are headed,” Mathioudakis said.
Tight-lipped
Elevate Ventures has declined IBJ’s request for interviews since late April, a few days after the funding freeze went into effect.
And IEDC officials have been selective about what they are willing to say. They have answered some of IBJ’s questions but not others. They have also shared some Elevate-related documents that IBJ did not ask for while the agency has not sent other documents IBJ specifically requested.
Braun skirted a direct question from IBJ last month about why the IEDC decided to request repayment of the 2011 loan rather than convert it to an ownership stake in the loan fund, an option spelled out in the original loan documents and one that Elevate officials have said was anticipated from the earliest days of the IEDC/Elevate relationship.
Referring to the IEDC’s decision to call the loan, Braun—who chairs the IEDC board—said, “I don’t know the reason why they would have done that or not done that.”
“My opinion would be that if there’s going to be a plan to get [the loan repaid] and do it in a timely manner, it’d be worth listening to,” he said. He added that the process will be “fully transparent.”
But Banner and others say they want more insight into what’s happening. “I really cannot tell what’s going on here,” he said. “I feel like there’s a lack of transparency here.”
Banner said he’s known Elevate CEO Christopher Day and many of the organization’s other leaders for a long time, “and they don’t strike me as people to do something that would not be aboveboard.”
Mathioudakis, too, said Elevate is well-regarded. “I certainly don’t have any reason to believe there’s any malfeasance,” he told IBJ.
Banner said he would be “very shocked” if Elevate is found to have committed wrongdoing. But more than anything, he just wants clarity about what’s going on.
“I just want to know. I think we all just want to know,” he said. “If there’s really a real concern with Elevate, let’s hear it out and let’s understand what it is.”
Key developments
From the outside, it’s difficult to know what to make of the things that have happened in the last several months between Elevate and the IEDC.
In a July 3 email to Elevate Ventures, Secretary of Commerce David Adams said his office believed that there had been “a material breach in the agreement between the IEDC and Elevate Ventures.”
Adams said that his office was invoking a 60-day period during which the parties would seek a resolution. During that period, Adams said the IEDC would “work to unlock the funds to pay your past and future invoices” per the terms of the parties’ professional services agreement. On July 17 and July 23, IEDC sent those payments, representing the monthly amounts due to Elevate for April, May and June.
Then on Aug. 1, the IEDC sent a letter to Elevate formally asking the organization to repay the 2011 loan that matured the next day. The loan was the instrument through which the IEDC had provided Elevate with the initial funds the state wanted it to invest in early-stage startups.
In the 2011 agreement, the loan had been described as a convertible note, meaning that the state could have chosen either to call the loan when due or convert it into ownership in the loan fund, a move that would have enabled Elevate to reinvest returns it had received from its initial investments into more startups.
Elevate wired a $12.86 million repayment to the state on Aug. 4. It told the IEDC that the remaining loan proceeds were still tied up in investments. Essentially, the fund that had been created with the loan’s original proceeds was part owner of several companies—ownership that Elevate estimated was worth $7.3 million.
Still, with that money tied up, Elevate said it did not have available money in the fund to repay the remaining $4.3 million the state said it owed.
The next day, the IEDC declared Elevate to be in default.
Then in an Aug. 13 letter to Elevate, the IEDC said it was freezing all of Elevate’s accounts over “unreconciled, ongoing concern” about the nonprofit’s ability to fulfill “any of its current or future obligations.”
The letter also asked Elevate to cease performing, or spending money on, any ancillary services.
The IEDC would not answer IBJ’s question about what authority it has to freeze accounts that are in the name of Elevate, not the state. Meanwhile, Elevate has continued to host activities and promote them online.
A ‘false choice’?
Since taking office in January, Braun has expressed his wish to support “Main Street” businesses. That term generally refers to companies that are not easily scalable, typically don’t attract venture funding and can be found in communities across the state—companies such as manufacturers, retailers, construction companies and service providers.
In launching the state’s new Office of Entrepreneurship and Innovation in July, Braun’s administration described the office’s goal as that of helping “Main Street entrepreneurs start, grow and scale their businesses to grow Indiana’s economy and support Hoosier workers.”
Andersen, of High Alpha, said he has no insight into the Braun administration’s goals or what’s happening with Elevate. But he warned against what he sees as a “false choice” between supporting Main Street businesses and high-growth startups. High Alpha’s focus is on business-to-business software startups, which involve a lot of risk of failure but also the potential for huge rewards if they succeed.
There’s no silver bullet for achieving economic growth, Andersen said. Instead, it takes essentially a shotgun approach—deploying simultaneous strategies for supporting many types of businesses.
“The reality is, we need a lot of lead bullets related to Main Street small business, and we need a lot of lead bullets related to these high-growth startups,” Andersen said. “I think we should be investing ambitiously and aggressively in both of those parallel strategies.”
As the uncertainty around Elevate drags on, Andersen said, the conflict creates damage overall for Indiana’s reputation.
“I don’t love the idea of Elevate being castigated this way. I think it’s bad for Indiana,” he said. “I think it’s a bad look. I think it has a chilling effect on external capital.”
“This feels a bit like an insular posture, and I think that has implications,” he added.
And on a more immediate level, observers say, the longer Elevate is prohibited from investing in new startups, the more those startups will suffer.
“The tech community moves very fast,” Mathioudakis said. “Four months in the life cycle of an early-stage company? It’s almost like dog years.”
And Elevate’s mandate to act as a co-investor in companies—never the sole investor—inspired other investors to join funding rounds, he added. They saw Elevate’s participation as a stamp of approval for a startup.
“Angel investors were comforted when they knew Elevate was investing,” Mathoudakis said.
Impact on Rally
The friction between Elevate and the IEDC also appears to be having some negative impact on the Rally innovation conference, which is set to take place Sept. 24-25at the Indiana Convention Center.
Elevate launched the event in 2023 as a catalyst for sparking entrepreneurship and innovation in Indiana across multiple industries, including software, sports tech, food and agriculture and others. The gathering, which drew about 3,000 participants in each of its first two years, included nationally known keynote speakers, five pitch contests offering big-money prizes, workshops, networking opportunities and more.
Elevate officials have declined to answer IBJ’s questions about how many tickets it has sold for the 2025 event or about its revenue from sponsors and other sources.
But the IEDC, which is allowed under its contract with Elevate to have an observer at the nonprofit’s board meetings, gave IBJ select pages from a packet distributed to board members for Elevate’s July 30 meeting.
Those pages detailed Rally’s financial picture as of July 23 and outlined some of Elevate’s concerns about the impact its conflict with the state was having on the event. When IBJ asked questions about the board packet last month, the IEDC acknowledged it had released only some of the pages. And despite IBJ’s requests, the agency has not released the full packet.
In the pages released by the IEDC, Elevate said “unknown parties” had reached out to Rally keynote speakers to try to persuade them to back out of their commitments to the event. It also said the IEDC had been telling entrepreneur-supporting organizations not to publicly support Elevate events.
Rally’s online schedule shows four keynote speakers: entrepreneur and business personality Kevin O’Leary; former skier, poker player and author Molly Bloom; Carmel-based composer and filmmaker Austin Gleckman; and entrepreneur and investor Chris Yeh.
IBJ reached out to those four speakers or their representatives but heard back from only one. In an e-mail, Yeh said no one had tried to persuade him not to attend Rally, “and I am eagerly looking forward to participating!”
In response to an IBJ query, IEDC spokeswoman Erin Sweitzer denied that the agency had done anything to discredit the event. “To the best of our knowledge, no one at the IEDC has been discouraging any speaker or entrepreneur to participate in Rally,” Sweitzer said via email.
In the same board packet, Elevate said the ongoing conflict with the IEDC had also hurt its ability to attract Rally sponsors. As of July 23, Rally had secured $317,775 in cash sponsorships and another $195,000 in in-kind donations, the slide deck said. But the presentation also said multiple sponsors had opted not to participate, representing more than $300,000 in financial support.
Sponsorships are especially important this year because the IEDC is not financially supporting the event, which has a budget of $1.59 million.
In 2023, the IEDC contributed $1.75 million toward the event’s $2.9 million budget. In 2024, the IEDC contributed $1 million toward the event’s $2.5 million budget.
One of the organization’s top goals for Rally 2025, the presentation said, is to meet its budgeted goal of securing at least $500,000 in sponsorships, which the presentation described as “critical” for the success of the event.
Because the presentation represented a snapshot in time, it’s possible Elevate has succeeded in attracting additional sponsorships. But the organization wouldn’t answer IBJ’s questions about sponsors.
Looking ahead, Andersen said he fully believes Indiana can regain its footing. Most states have some type of publicly supported entrepreneurship initiatives, he said, and “no city or state has done this perfectly. They’ve all taken two steps forward and one step back—and sometimes one step forward and two steps back.”
“My day job is getting knocked down and getting back up again,” Andersen said. “So, do I believe as a state we can do that? Yeah. I think we’re built to do that. But we do need to recognize that this is taking us in the wrong direction.”•
Editor’s note: This story has been corrected to reflect Jeb Banner’s status as former CEO of the software firm Opendate.
Please enable JavaScript to view this content.
Let’s start looking at the compensation of all these folks involved.
Exactly
“People in line to get free money experiencing angst because they might not get free money”
Fixed the headline for you IBJ
My grandmother warned about cutting off the nose to spite the face. Regardless of whether or not Elevate did anything out of line, why can’t the the Braun Administration find a way to address concerns without undue harm to Indiana’s burgeoning tech ecosystem? Politics and power spats only divert attention from the kind of problem-solving our citizens want to see from state leadership.
Susan, what a great article, very objective and detailed.
Indiana needs to stop investing in things that the private market won’t…because there is no market.
The only ones making money here are the VCs collecting fees.
From Hannah News:
“Then Sen. Qaddoura laid out the crux of his concerns, ostensibly to the IEDC proxy, but more so for his colleagues and those who may have been watching the meeting.
The same prospectus, the investment prospectus has language about conflict of interest and I will read it to you.
It said, and this is from directly coming out of their documents that they sent to investors – and the subheading is ‘Potential Conflicts of Interest with the Management Company,’ personnel of the management company and Elevate. Although personnel of the management company shall devote such portion of their time during normal business hours to the management and operation of the fund as may be necessary to effectively manage the fund’s business, the management company and its personnel are entitled to and do engage in other business activities, and are not prohibited from engaging in activities that are, or may be competitive with the activities of the fund specifically.
This is not from me. This is from the investment prospectus that they are sending around.
But I’m extremely concerned that we’re not getting anywhere with holding IEDC accountable, and we’re not getting the answers.
And I … hope that for those who are listening from IEDC, I demand that we as legislators need to know the answers to all of these transactions that are happening under IEDC, funded by the taxpayers going to IEDC ventures – from IEDC to Elevate Ventures, Elevate Management, LLC, Rally Innovation LLC – and the key employees are getting paid with conflict of interest that exists and acknowledged by their own prospectus investments.
I don’t think this is right. It’s just not right for the taxpayers of the state.”